I previously covered the financial and product trajectory of Anthropic and OpenAI back in September. It's finally time for a deeper look at Anthropic this week as it IPOs.
This first post covers the financials and corporate profile detailed in its S-1. A second post looks at agentic demand and the breadth of its platform. A later follow-up post will take a detailed walk across future buildout commitments and partners.
- This company is a rocketship, and I haven’t seen another company improve gross and operating margins this fast while growing revenue at this pace.
- Revenue grew 12-fold over the past year, and nearly +47% sequentially. Anthropic generated nearly $17B in revenue in Q3, delivering more revenue than the entire first half of the year.
- Its revenue run-rate reached $81B in October, up from $71B in September, $65B in July, and $9B at the end of 2025.
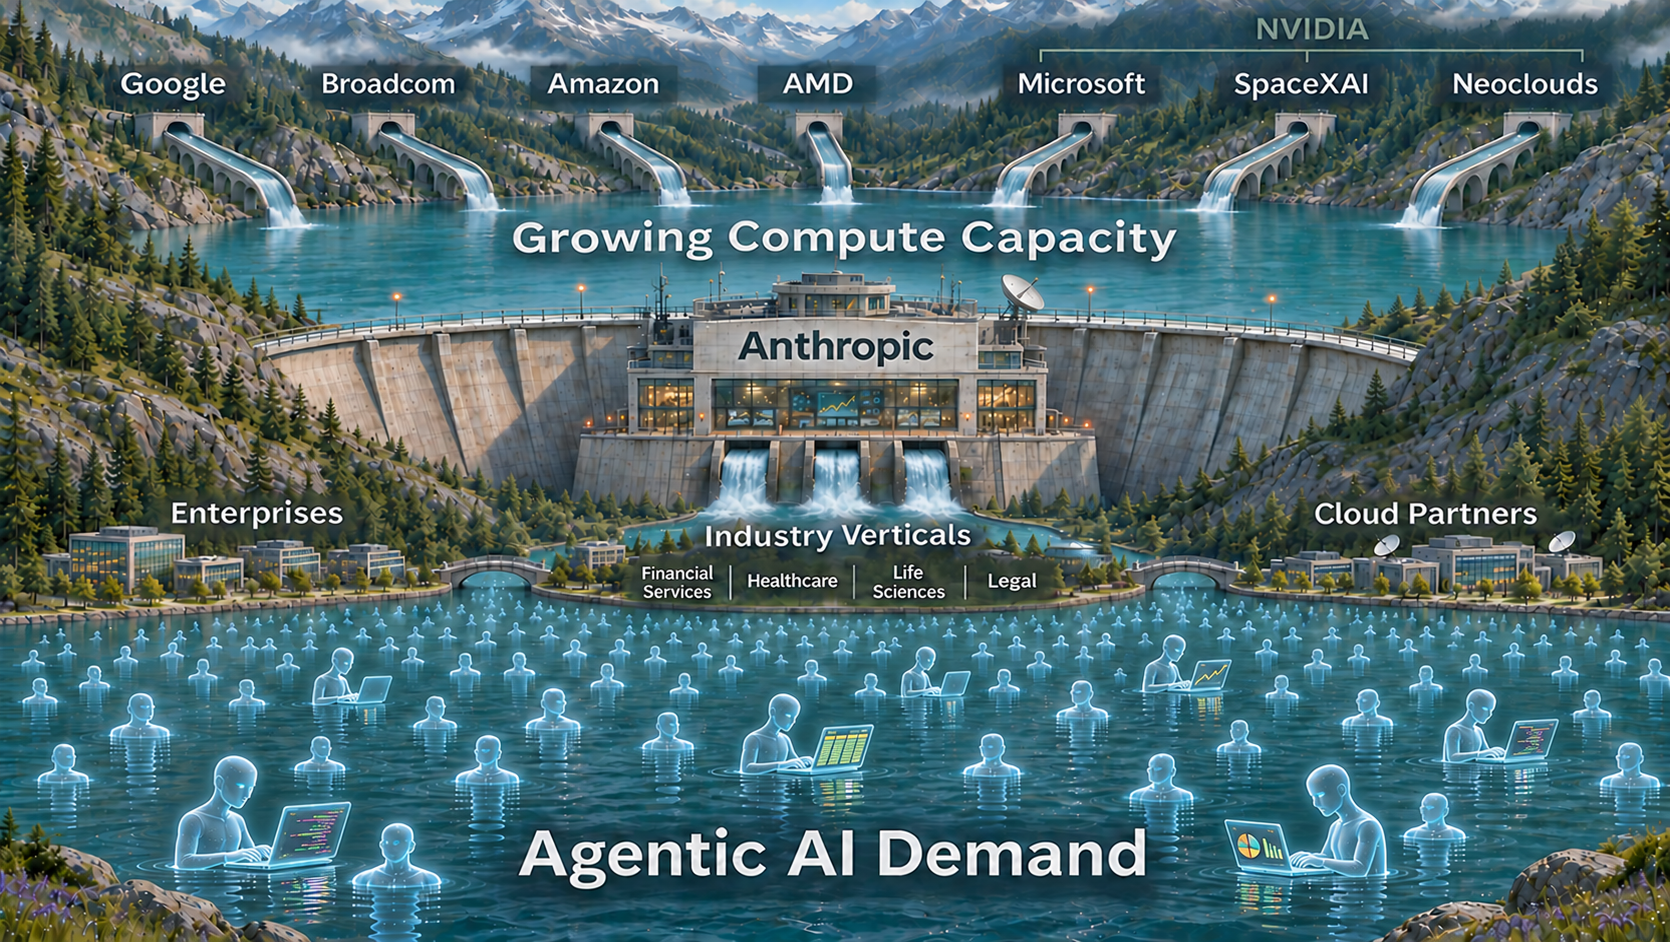
- Agentic workloads are surging, and that consumption is driving nearly 80% of revenue. Autonomous agentic capabilities in coding are now spreading into knowledge work and cybersecurity.
- Mgmt cautions that they saw a 20% reduction in usage over the last 2 weeks of 2025, due to code freezes and holidays. I'm not sure that's as much of a worry this Q4, given the drastic rise in long-running agentic workloads.
- This massive scale-up of agentic demand has significantly improved its profitability profile as operating and computing leverage kicks in. YTD gross margin jumped from 29% to 85% over the past year.
- They went from deeply unprofitable GAAP operating margins all of last year (-249% to -139%) to swinging positive (+8.4%) last quarter. Astounding.
- That stellar margin trajectory was impacted in Q3 after spending $5B on short-term compute, paying a premium for capacity before longer-term supply comes online.
- Large customers have also grown 12-fold YoY, and they are also reporting strong customer cohorts with over $1M and $10M in annual spend.
- Customer concentration is improving, with its top 5 customers falling from 36% to 25% of the mix over the last 2Qs. They also have a long tail of 40M smaller customers.
- AI is clearly spreading into other enterprise workloads. NRR is ~900%.
- Marketplaces are providing 48% of revenue. They are leveraging partnerships with the top 3 hyperscale clouds to drive model use, plus are now providing a fully embedded platform within AWS and GCP.
- They have commoditized their compute capacity across multiple chip providers and hyperscaler cloud & neocloud providers. They are continually optimizing and improving the efficiency of that compute ("compute multipliers") to make greater use of that pool.
I think interest will be heavy as they hit the public market on Thursday. I am interested in shares, but not if it drastically jumps out of the gate. There will also likely be some opportunities to buy over the coming weeks and months, as immediate and staggered lockups expire and the market's volatile mood for AI names shifts.
Part 1:
- Latest financials
- Corporate & share structure
- Fungible compute pool
- Compute efficiency
Part 2:
- Agentic acceleration
- GTM motions
- Competitive landscape
- Platform and products